Lifestyle
She Planned to Work Until 70, but at 64 Her Body Said Otherwise. Now She’ll Rely on Social Security in a Small Cottage: “I Have Everything I Need”
By Mike Harper · November 21, 2026
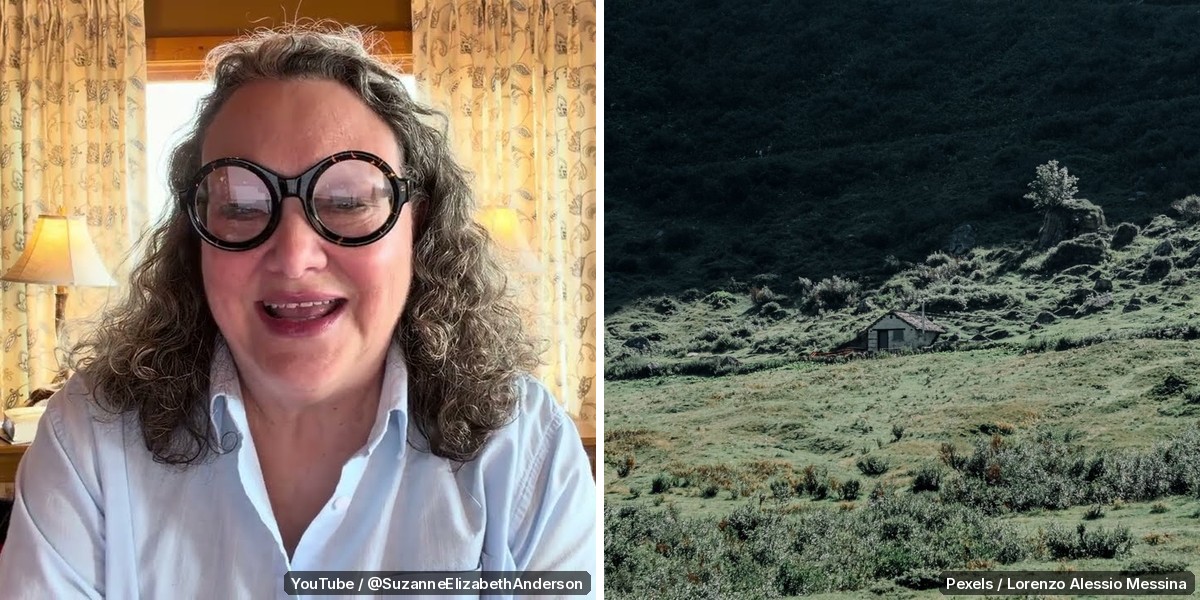
Suzanne had a clear plan for the last stretch of her working life. She would keep her remote customer service job until 70, keep adding to her 401(k), and wait as long as possible to claim Social Security.
“So I had had a plan. I planned to work until I was 70. Financially I needed to,” she says in a June 2026 video on her YouTube channel, @SuzanneElizabethAnderson.
Then one Monday morning, sitting at her work desk before her first call of the day, she had a frightening health scare. She told her manager, called in sick and saw her doctor the next day. Over the following week she came to see it as a sign that she could not keep pushing. “But my body said something else.”
“If you’re new here, my name is Suzanne. I’m 64 years old. I live alone in a small cottage in rural North Carolina,” she says. She moved to the western part of the state from Colorado about three years ago.
She spent that week writing out all of her expenses and checking her estimates on the my Social Security website. Her thinking shifted step by step. What if she worked until 67 instead of 70? What if she worked one more year, to 65? In the end, she decided she could not keep working, and she would retire and claim her benefit now.
She is honest about what that means for her budget. “I have a small amount of money saved that I’ve saved over the last three years since I moved here, but I will be relying on social security as my income,” she says.
She also knows the tradeoff. “By taking social security at 64 my monthly payments are going to obviously be a lot smaller than they would be if I waited longer.”
Still, the week left her at peace with the choice. “But here’s what I kept coming back to all week. I have everything I need.” She lives simply, she says, and her cottage is small and just right for her.
The gap she accepted is a real one. For anyone born in 1960 or later, full retirement age is 67, according to the Social Security Administration. Claiming at 64 pays 80 percent of the full benefit. Waiting past 67 earns delayed retirement credits of 8 percent a year until 70, when the increase stops. That works out to 124 percent of the full amount at 70. In other words, a person due $1,000 a month at 67 would get about $800 at 64 and about $1,240 at 70.
The SSA notes that claiming early has an upside too: benefits are collected for a longer period. Each person’s situation is different, the agency says.
Anyone facing a similar choice can start where Suzanne did. Sign in to my Social Security at ssa.gov to see personal estimates at different ages, and list monthly expenses next to that number. Remember that Medicare starts at 65, so someone who stops working earlier needs a plan for health coverage in between. And if a health problem is forcing the question, talk with a doctor first. Anyone with sudden chest pain or trouble breathing should call 911.
This article is for general information and is not financial or medical advice. Suzanne’s story and quotes are from her YouTube video. This article was produced with the assistance of AI and fact-checked against the sources cited by LightWave Reports.